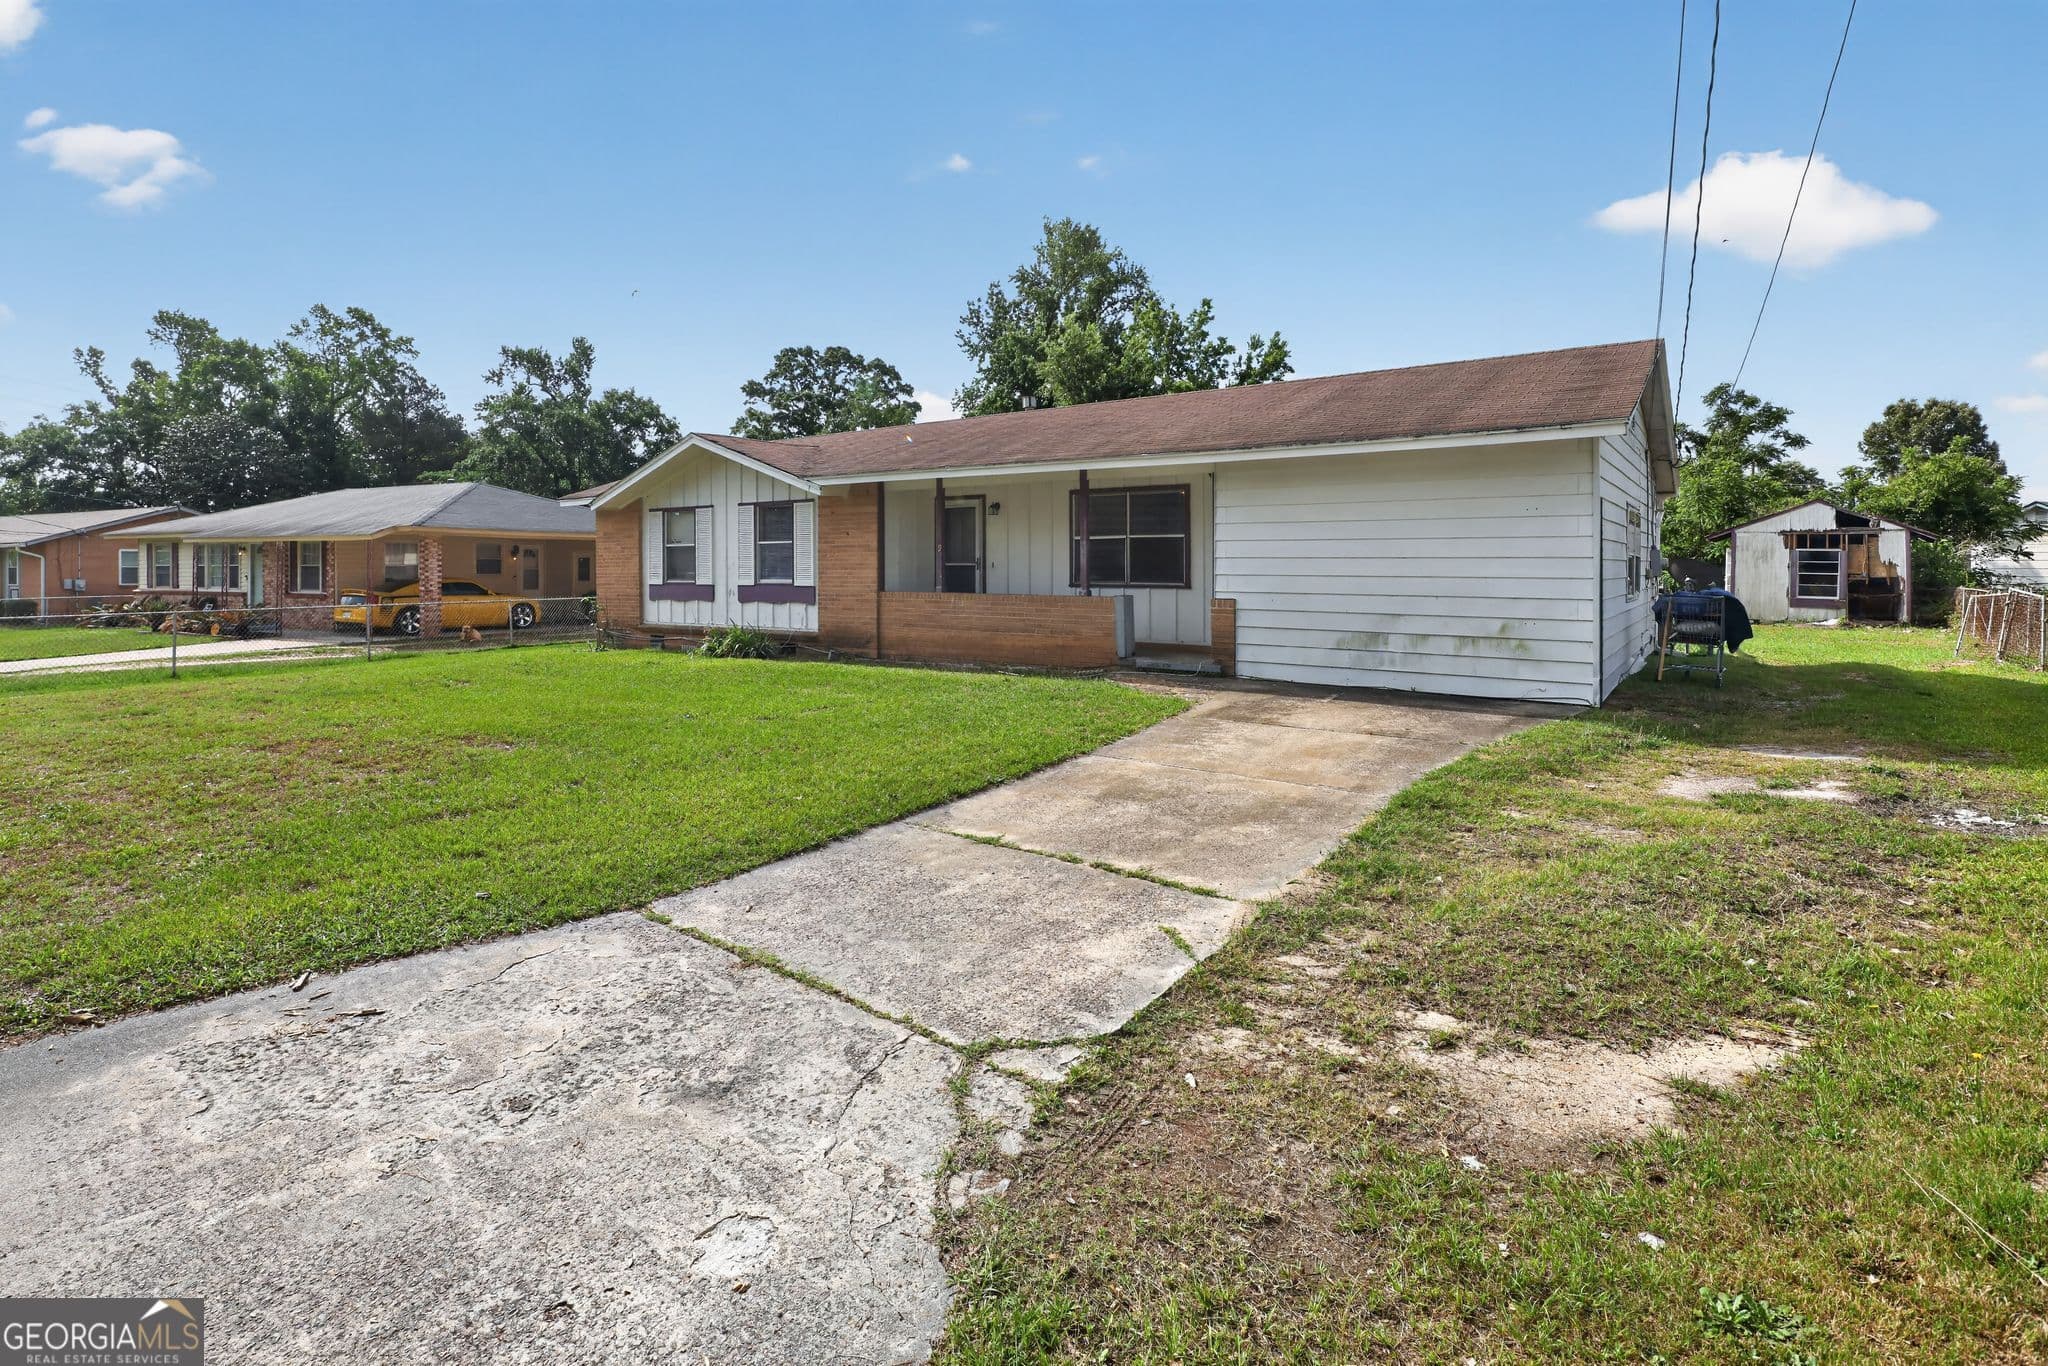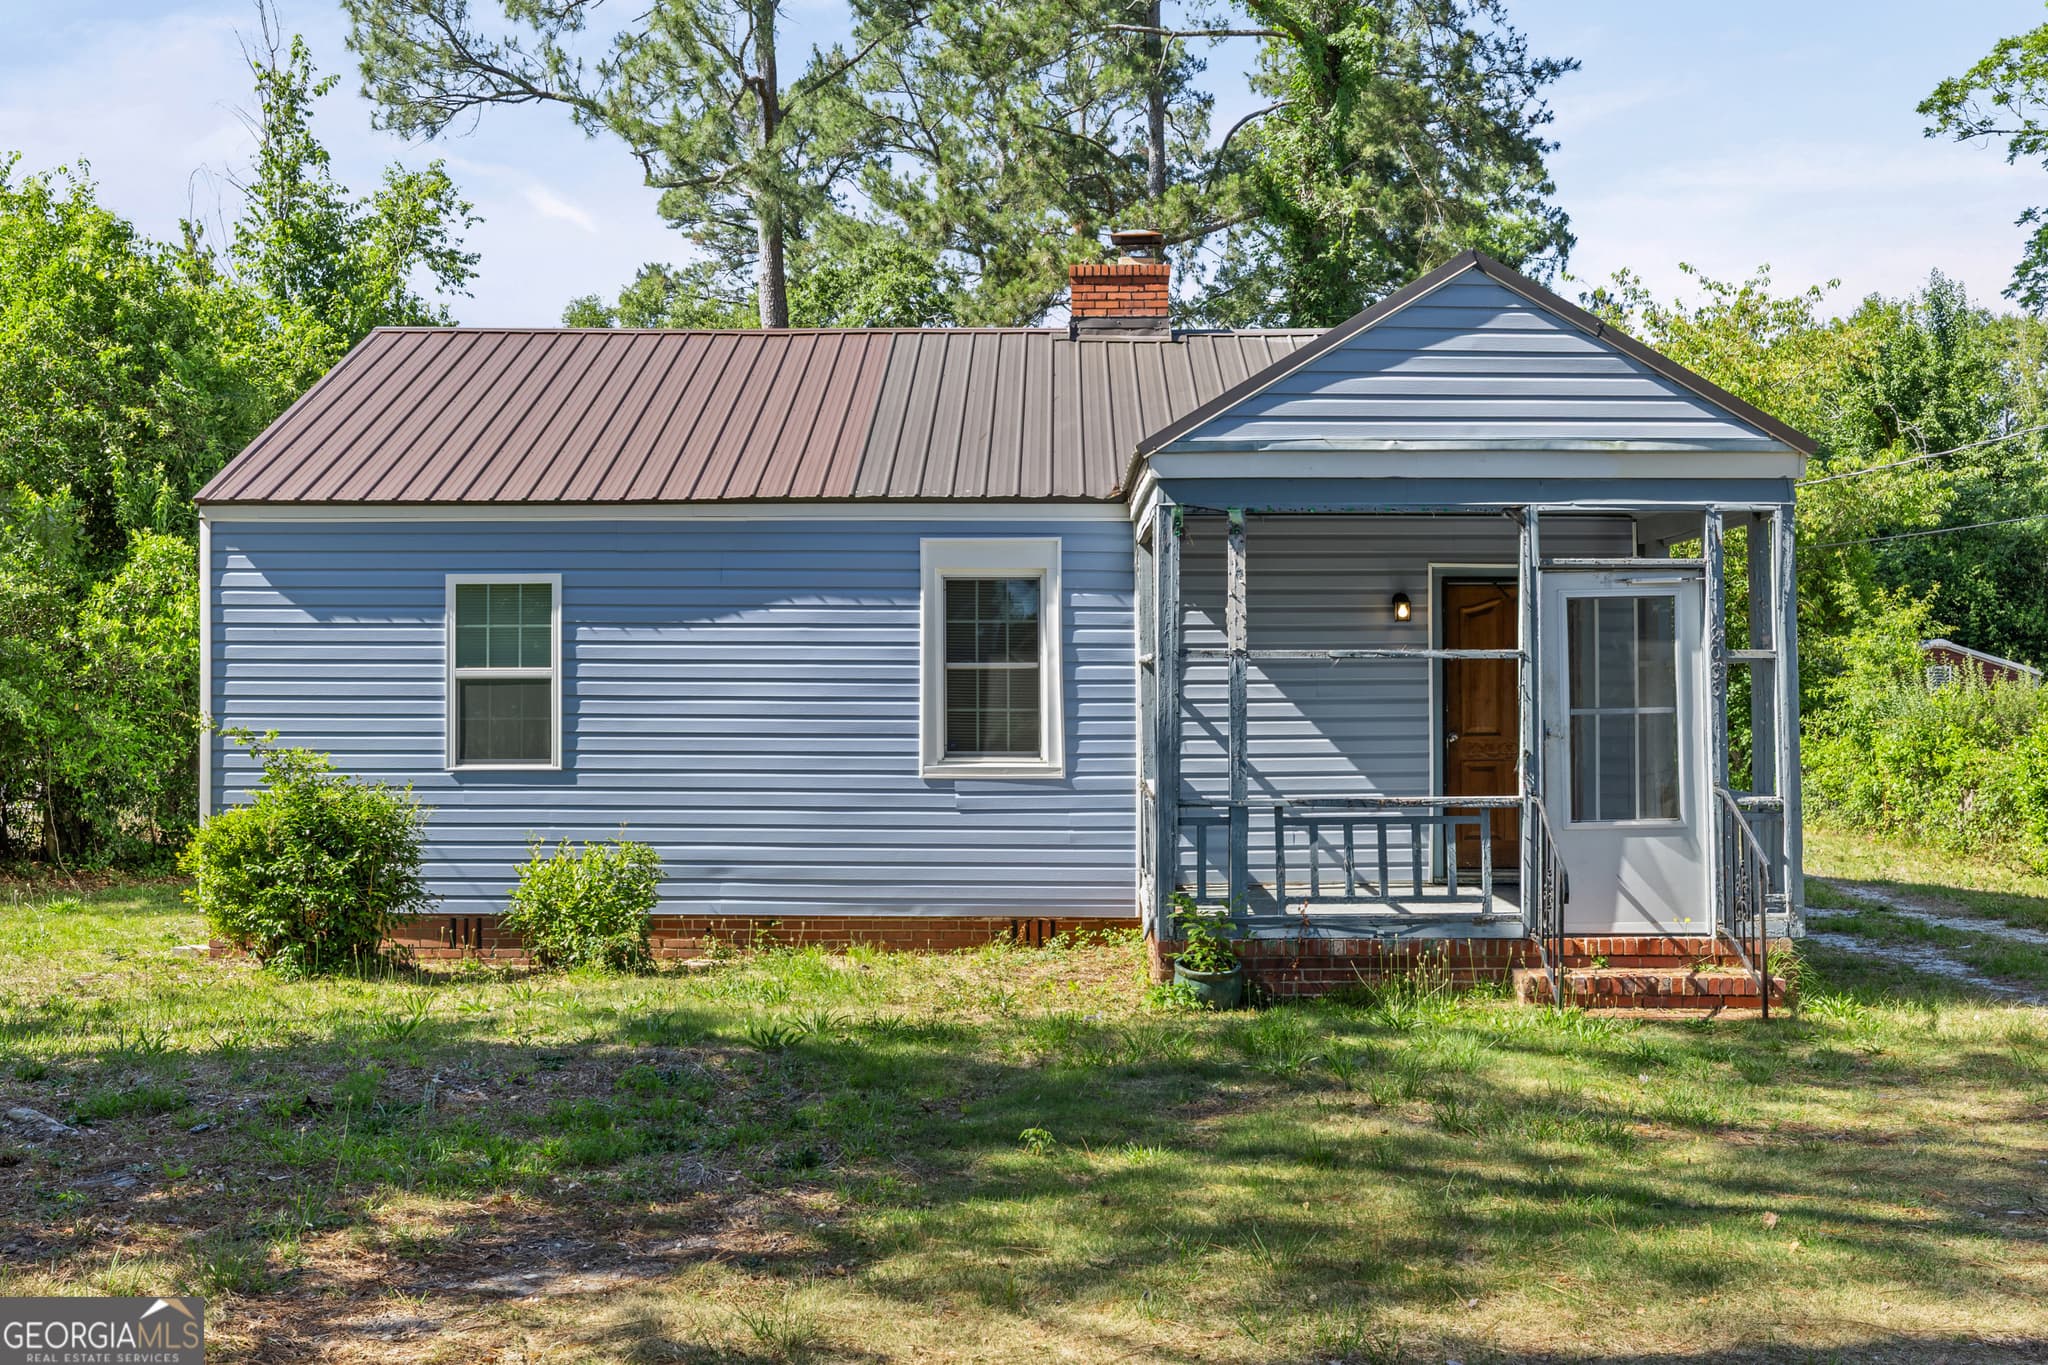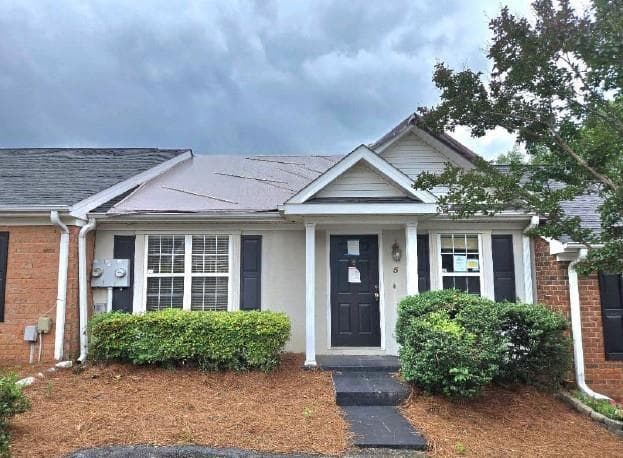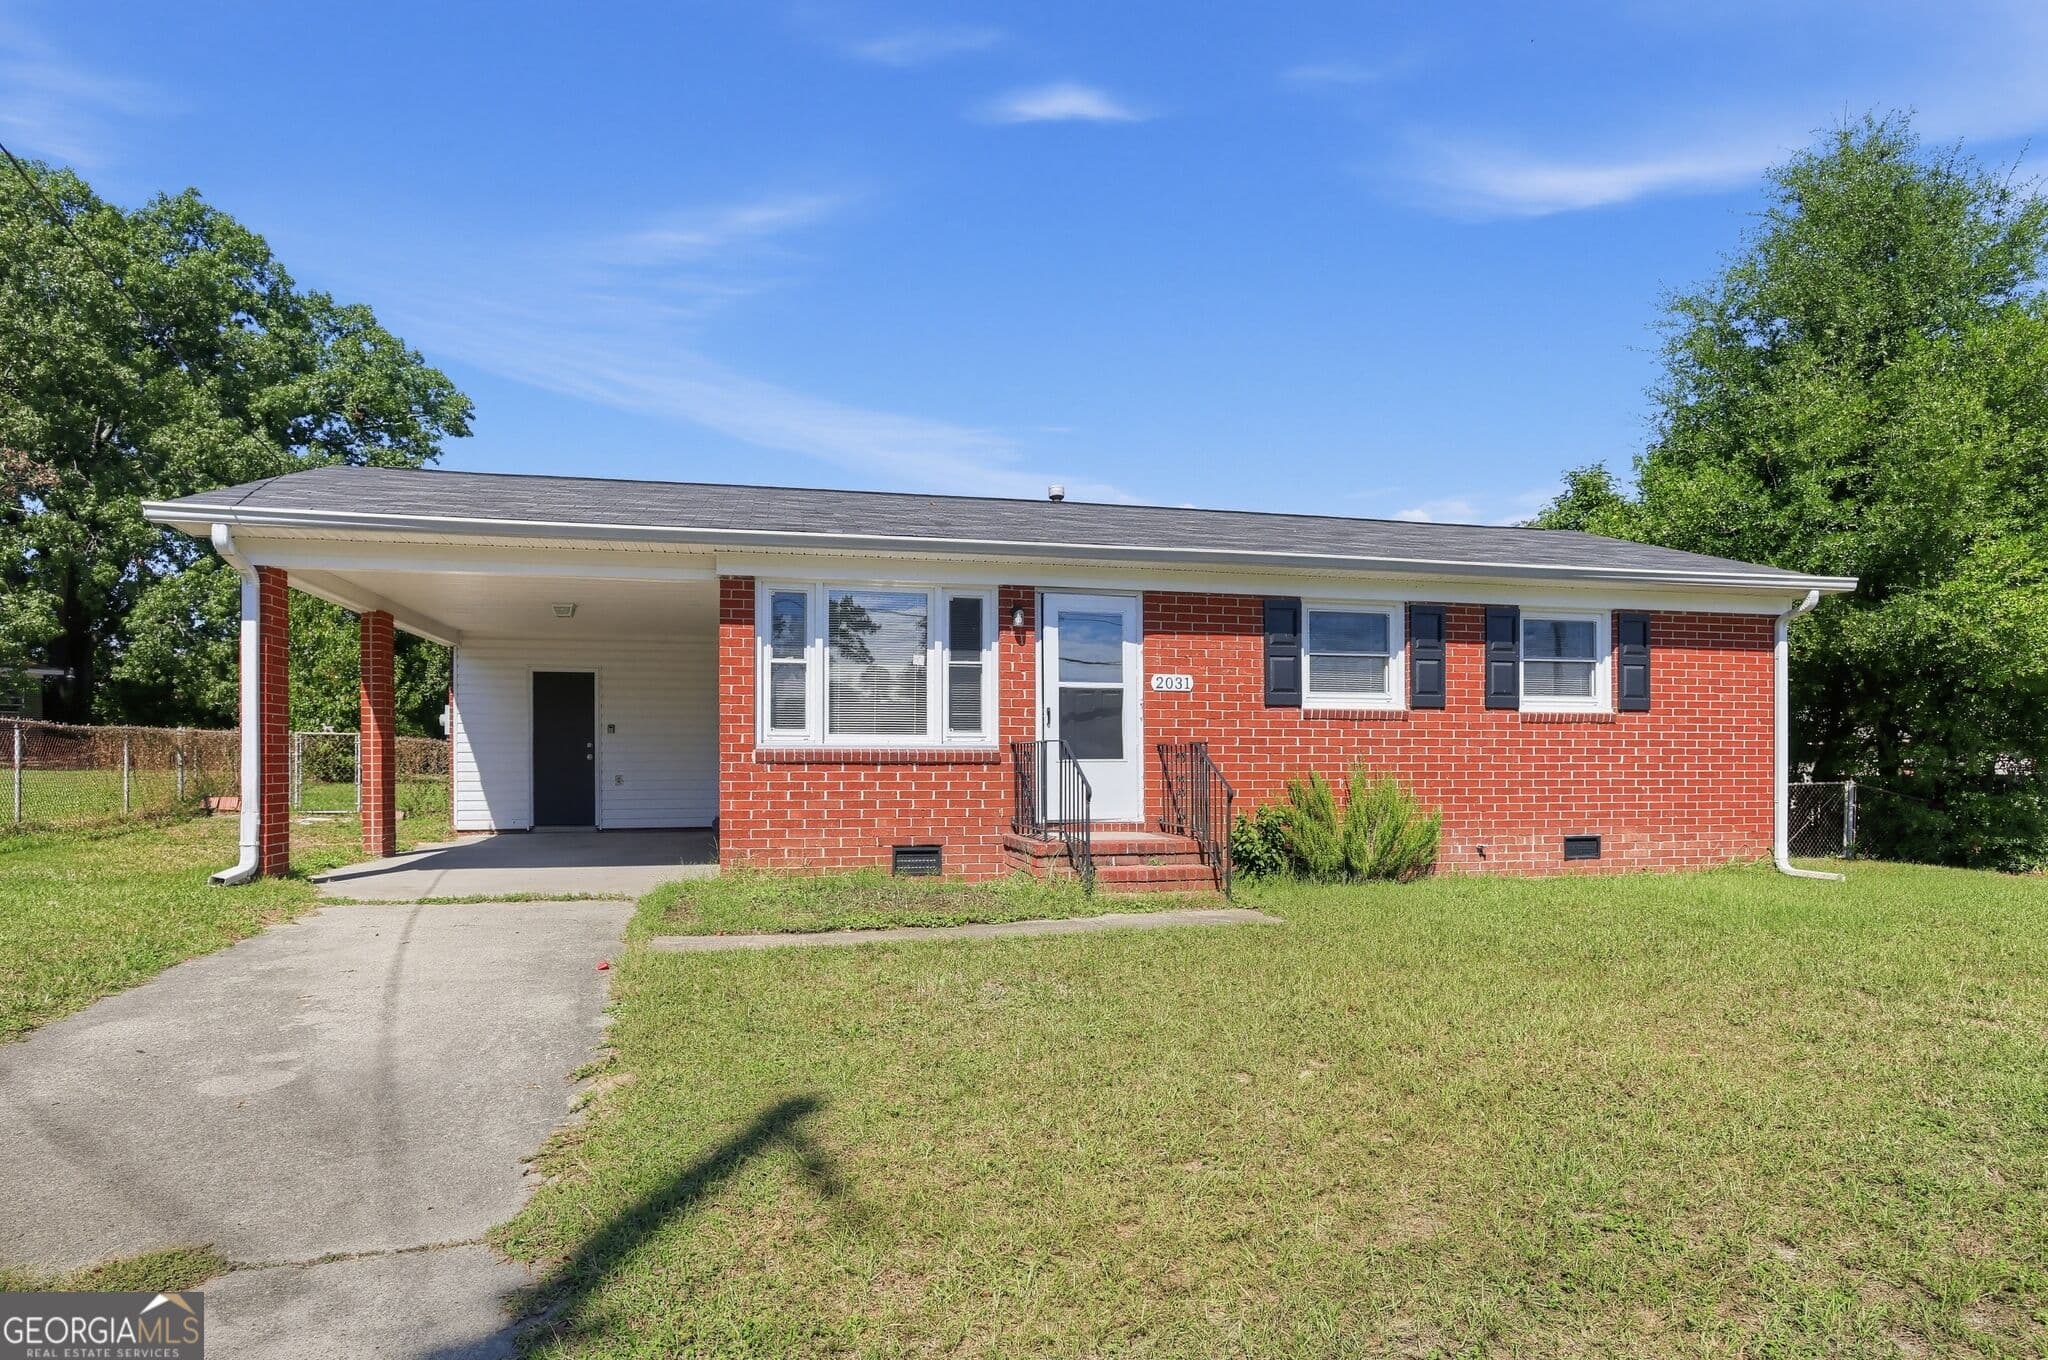
· GAMLS #10856011Fewer than 3 renovated homes like this sold within 3 miles in the last 18 months, so we don’t estimate an after-repair value. Enter your own, or ask a Veribas agent to pull comps.
Investor figures are automated estimates, not an appraisal or an offer of financing. The after-repair value is the median price per square foot of renovated homes that sold nearby in the last 18 months, applied to this home’s size; rehab and holding costs are typical budgets, not a contractor’s bid. Walk the home with a contractor and confirm the comps with your agent before you offer.
Rates, lenders, terms and balances come from three places only: the listing agent's own remarks; the FHA loan in HUD's public FHA Single Family Portfolio Snapshot that matches the owner's recorded MLS purchase to the dollar (shown as "Likely"; the lender named is the loan's original lender, which may no longer service it, and the balance is the original loan paid down on schedule, so the loan may since have been refinanced, modified or paid down faster); or a Veribas agent's confirmation with the listing agent. A rate is shown when the listing description states it (labelled as such) or when its lender and loan term are known; payments are shown only when the lender and term are known. Otherwise ask and we'll get them. Rates shown are the existing loan's note rate, not an annual percentage rate (APR), and not an offer of credit from Veribas. Payments shown are principal, interest and estimated property taxes; homeowners insurance, FHA mortgage insurance, VA or FHA assumption fees and HOA dues are extra, so the actual payment will be higher. Down payments assume a second loan at 8.5% over 30 years up to 90% of the price combined; that is an illustration, not a loan offer. The loan servicer (and, for VA loans, the VA) approves every assumption, and the buyer must qualify. VA loans can be assumed by non-veterans, but the seller's VA entitlement stays tied to the loan unless the buyer is a veteran who substitutes theirs. Verify the rate, lender, term and balance with the listing agent before you offer.

Programs are published by the lenders, who set and confirm eligibility. The home's census tract is one requirement; buyer income, credit and other rules also apply.