Homes With Assumable Loans in Canton, GA
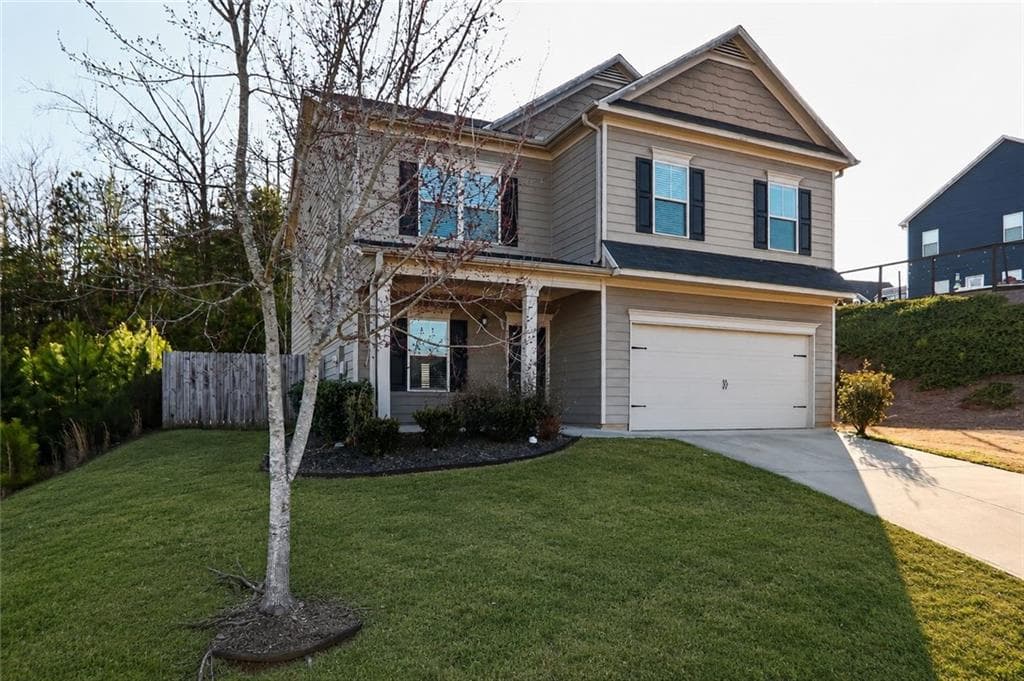
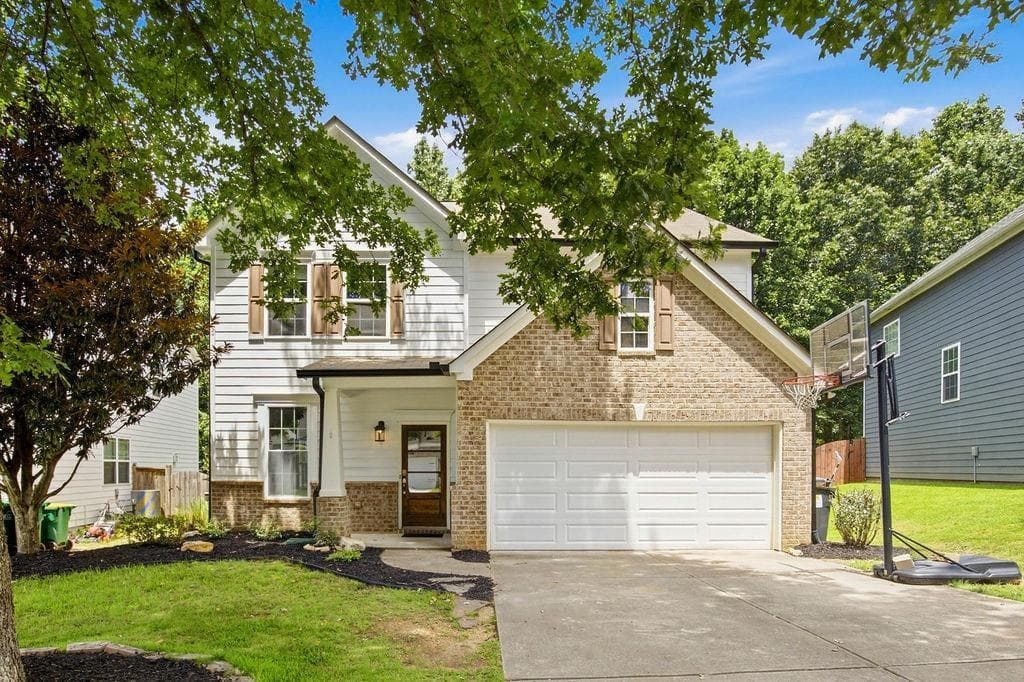
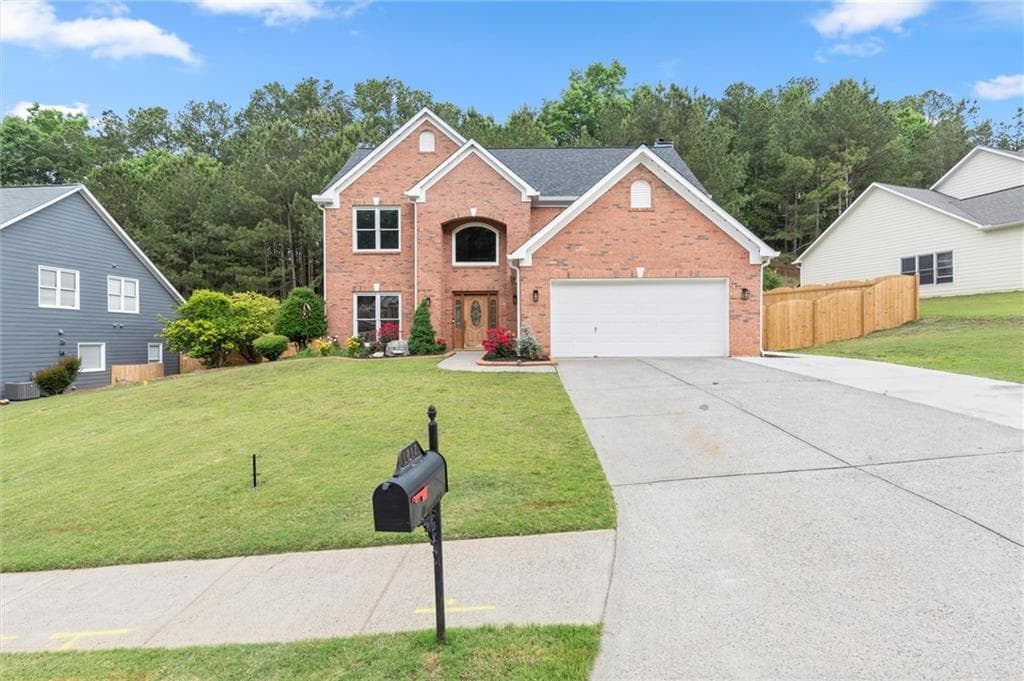
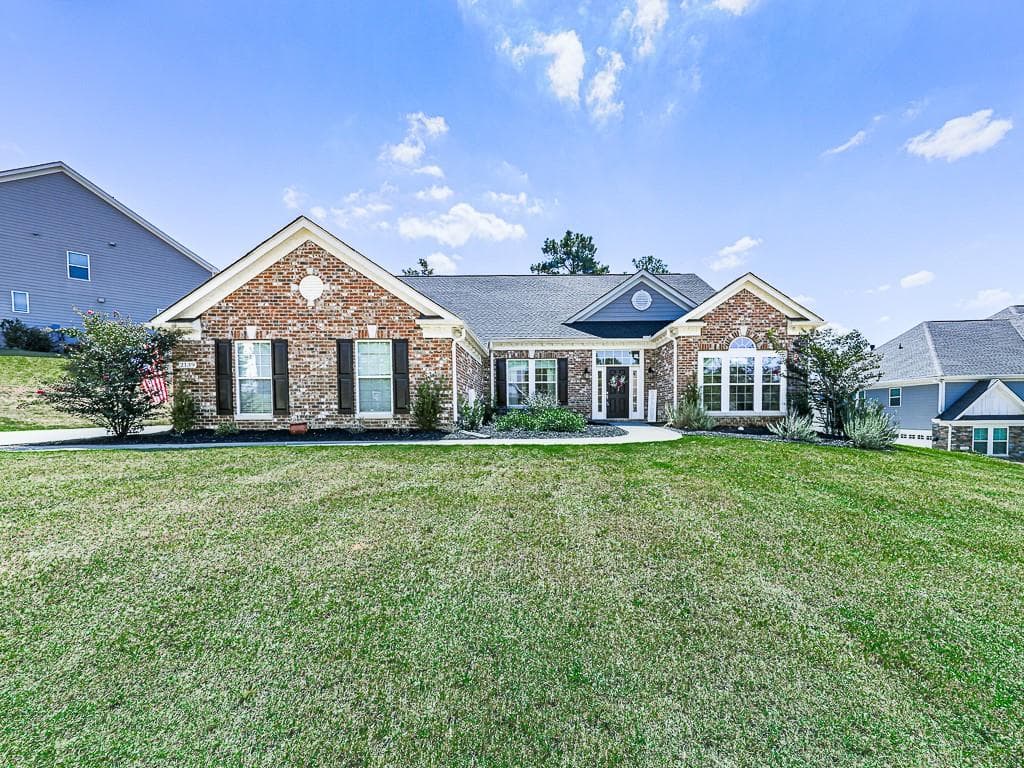
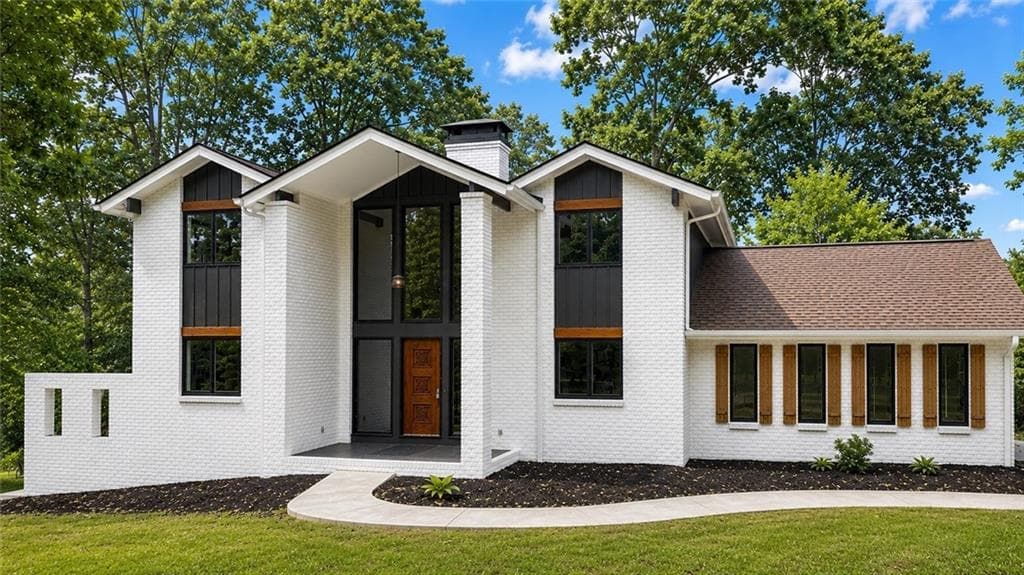
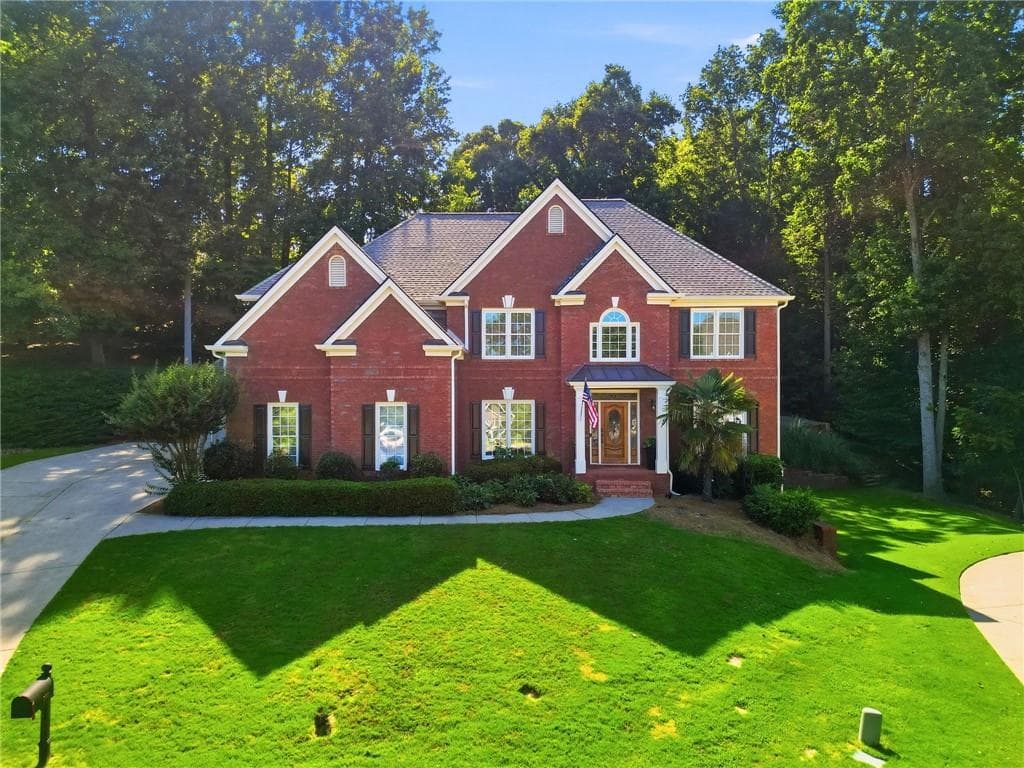
11 homes for sale in Canton, GA where you can take over the seller’s mortgage and keep their rate. Rates are as each listing states them, or with the lender and loan term.
- 1Keep the seller’s rateYou take over their FHA, VA or USDA loan, at their rate instead of today’s 6.75%.
- 2Put about 10% downA second loan covers the rest of the price. Both are in the monthly payment.
- 3Pay less each monthEach home shows its estimated monthly payment next to a new loan’s.
10 of these homes don’t publish the loan details, so we can’t work out the payment. Open the home and ask: a Veribas agent gets the real figures.
Assumable loan homes near Canton
Assumable loans in Canton, GA: questions
How many homes for sale in Canton, GA have an assumable loan?
11 homes for sale in Canton, GA have an FHA, VA or USDA loan a qualified buyer may be able to take over: 3 described by the listing agent, 6 matched to HUD's public FHA records. The list updates as listings change.
What is the lowest assumable mortgage rate in Canton, GA?
2.375% (note rate, not an APR) on a VA loan, From the listing description · lender & term not published, on a home listed at $460,000 in Canton. A new 30-year loan runs about 6.75% today.
Which assumable home in Canton, GA needs the least cash to take over?
The smallest gap between price and loan balance is about $20,500 (estimated), on a home listed at $274,900 in Canton. The gap is what you bring in cash or finance with a second loan.
What is an assumable loan?
It is the seller's existing mortgage, which a buyer takes over instead of getting a new one. The buyer keeps the seller's interest rate, remaining balance and remaining term. FHA, VA and USDA loans allow this. Most conventional loans do not.
Who can assume an FHA or VA loan?
Any buyer the loan servicer approves. You do not need to be a veteran to assume a VA loan. The servicer checks credit and income much as a new lender would. The process usually takes longer than a new loan, often 45 to 90 days, so plan the closing date around it.
What about the difference between the price and the loan balance?
You pay it at closing, either in cash or with a second mortgage at today's rates. On a $400,000 home with a $280,000 balance, that is $120,000. The blended payment is still often well below a new loan for the whole amount, but run the numbers with a lender first.
What happens to a veteran seller's VA entitlement?
It stays tied to the loan until the loan is paid off, unless the buyer is an eligible veteran who substitutes their own entitlement. That is why some VA sellers prefer a veteran buyer, and why it is worth asking the listing agent up front.
Get the loan details before you offer
A Veribas agent can get the balance, servicer and assumption terms from the listing side. They can also have a lender price the gap, so you know the real monthly payment before you write an offer.